
Why Bank Transaction History Is Becoming the New Credit Score
For many years, the numerical credit score determined whether someone would receive a loan, a credit card, or even a […]
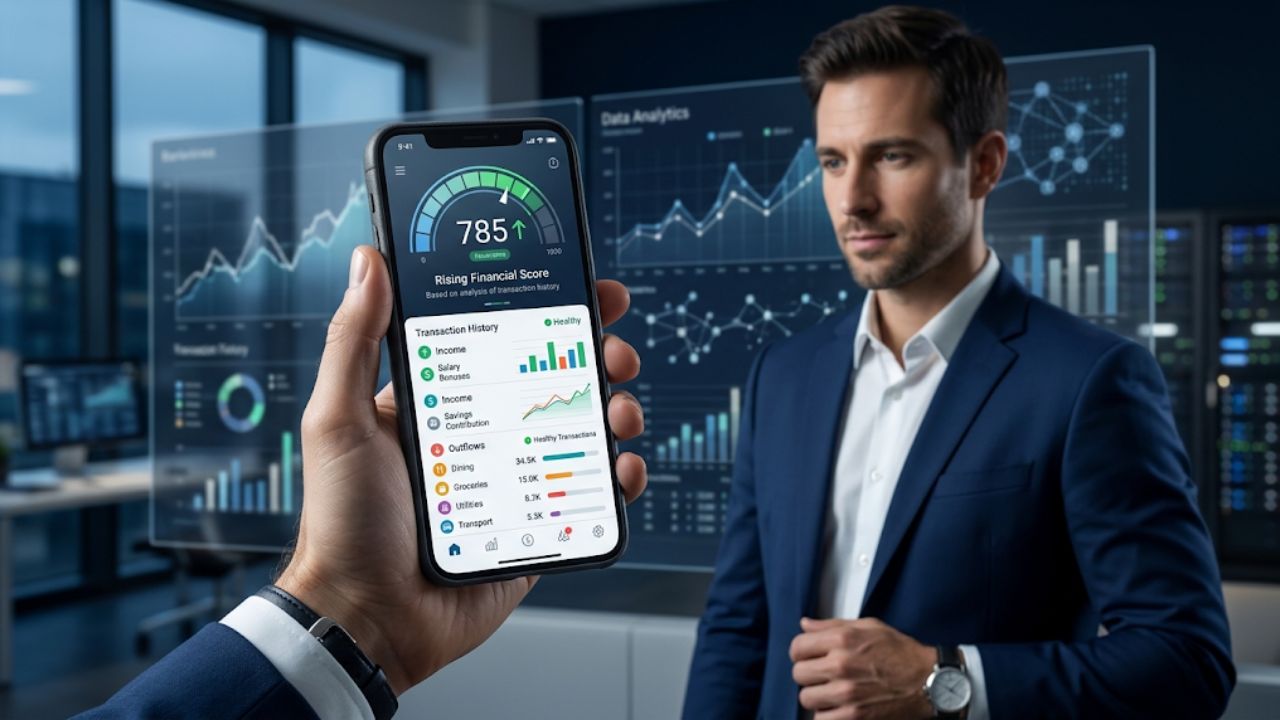
For many years, the numerical credit score determined whether someone would receive a loan, a credit card, or even a rental apartment. However, there are millions of people who are excluded from this scoring system because they do not have credit history. Today, lenders are turning to something everyone already has: bank transaction history. Your daily spending, saving, and bill payments are quietly becoming the new proof of financial trust. Through the analysis of cash flow trends, subscription fees, and utility bills, algorithmic underwriting can give a picture of a person’s creditworthiness at any one time. This is because the cash flow underwriting process enables people with “thin” credit records to demonstrate their fiscal responsibility. As such, open banking APIs are transforming financial prudence into a gateway to economic inclusion.
This shift matters because it’s fairer, faster, and based on real behavior — not just old debt records. There are credit platforms such as SwiftMoney that have already begun implementing this type of technology in order to increase the chances of credit approval without the need for a traditional score.
What Is Traditional Credit Scoring, and Why Is It Falling Short?
A traditional credit score (FICO/CIBIL) is made up of:
- Loan repayment history
- Credit card usage
- Length of credit history
- Number of credit inquiries
The problem: millions of people — students, gig workers, freelancers, and first-time earners — have little or no credit history. This is called being “credit invisible.” They may be financially responsible, but the old system can’t see it.
How Bank Transaction Data Tells a Better Story
Your bank statement shows real, live financial behavior. Lenders can now analyze:
- Regular salary or income deposits
- Monthly savings patterns
- Timely utility and rent payments
- Spending habits during emergencies
Example: Priya, a freelance graphic designer, has irregular income and no credit card. A traditional score would reject her. But her bank statements show consistent savings and on-time bill payments — data that proves she’s financially reliable.
The Simple Flow of Transaction-Based Credit Assessment
Here’s how it typically works:
Bank Account Data → Secure Data Sharing (with consent)
↓
AI/Algorithm Analyzes Patterns
↓
Behavior Score Generated (income stability, savings, spending)
↓
Lender Makes a Faster, Fairer Decision
The whole process takes mere minutes rather than days because there is no need to wait for the credit report from the credit bureaus.
Key Benefits of Transaction-Based Credit Scoring
Key points to remember:
- Faster approvals – Decisions happen in real time
- Inclusive – Helps people with no credit history
- More accurate – Reflects current financial behavior, not old debts
- Reduces bias – Focuses on actions, not assumptions
- Better for small loans – Ideal for microloans and short-term credit
Real-World Examples of This Shift in Action
- Gig economy workers using delivery or ride-share apps often get loan offers based on their weekly earnings pattern, not a credit score.
- Small business owners who accept digital payments can show steady cash flow to qualify for working capital loans.
- First-time credit users, like recent graduates, can use rent and subscription payment history to build trust with lenders.
Companies like SwiftMoney are part of this growing trend, using transaction insights to open up credit access to people traditional systems often overlook.
Points to Remember Before Sharing Your Bank Data
- Always ensure the safety and RBI compliance of the platform
- Understand the nature and extent of data sharing
- Look for clear consent options — you should be able to opt out anytime
- Compare offers, since interest rates can still vary by lender
- Keep your account activity consistent and transparent
The Future: A Fairer Credit System for Everyone
Bank transaction history won’t fully replace traditional credit scores overnight, but it’s closing a major gap. It gives a voice to people who were previously invisible to lenders — based on real financial habits, not paperwork from the past.
As more platforms adopt this model, borrowing money may soon depend less on how long you’ve had credit, and more on how responsibly you manage the money you already have. In a world moving toward smarter, data-driven finance, tools are helping shape what a truly fair credit system looks like.
Keep Exploring Zingyzon.com
Read more Zingyzon SEO, digital marketing, online earning, business, and technology guides for Australia, USA, and global readers.